Financial Therapist, Money Coach, or Financial Advisor: Who Actually Helps With What?
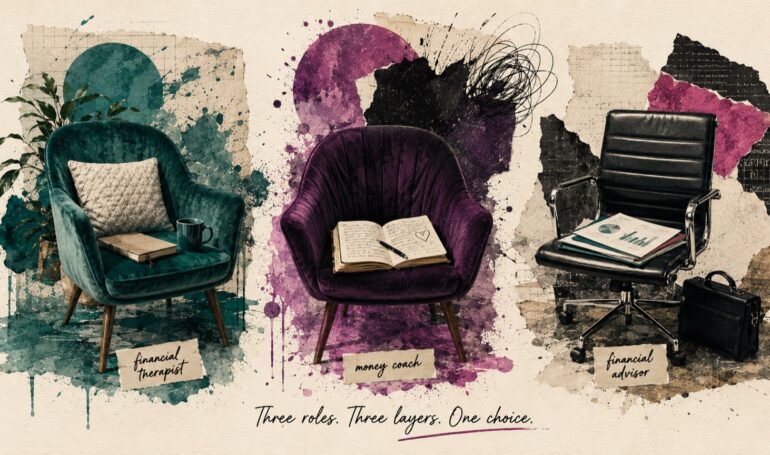
Which of the three you need is decided by the layer your problem is living on, not by the label on the door. You can usually feel that layer long before you can name the person who works it. A financial therapist works where financial behavior and emotional or relational wellbeing meet. A money coach works the gap between the decision you know how to make and the one you keep postponing. A financial advisor works your personal assets, usually your investments and your long-range plan. Hire on the problem, not the title.
And if you already sensed that, but still can’t tell which one to call on a Tuesday, you’re reading a messy market accurately. All three labels are used loosely online. Financial therapy and money coaching aren’t federally regulated titles, while investment advice about securities is regulated and registration can be checked. You went looking for a professional. What you found was vocabulary.
The stall has a price attached, and it gets charged twice. Picking the wrong chair costs money, and it also costs the small amount of nerve it took to admit you needed help at all. The second cost is the expensive one, because you can’t re-earn it on demand. So the picking gets postponed, and the problem keeps compounding quietly in the background.
The regulation matters, because it tells you what a title guarantees. The scope matters more, because it tells you what actually happens in the room. And the honest answer for most established owners is that they need two of these at once, in a particular order. Prosperity First works with service business owners who are earning real money and still can’t get a clean decision out of their own numbers. Shaneh Woods is a money coach and fractional CFO with 30+ years in finance. She’s not a therapist, not a CPA, and not a financial advisor.
Estimated reading time: 13 min read
TLDR: Before the full guide
Financial therapy sits where money and mental health meet, and the practice area isn’t regulated in the United States, so the individual practitioner’s license is the thing to check. Money coaching is present and future work on decisions, behavior, and follow-through, and it’s not clinical care. Financial advice about securities is a regulated activity, and the person doing it is generally registered with the SEC or a state authority. Below: what each one does, what each title guarantees, the fourth chair most comparisons forget, and how to match yourself to the right one.
Keep reading for the complete guide.
What this guide covers
- Start With the Problem, Not the Title
- The Financial Therapist: Money Where It Meets Mental Health
- The Money Coach: Where Knowing Turns Into Doing
- The Financial Advisor: Your Personal Assets, Under a Regulator’s Eye
- The Fourth Chair Most Comparisons Leave Out
- What Each Title Actually Guarantees
- Matching the Chair to the Sentence in Your Head
- Where Prosperity First Sits
Start With the Problem, Not the Title
Most comparisons line the three of them up like competing products. They’re not competing. They sit on different layers of the same money, and each one answers a different question. Yours is usually one of these:
- I feel something about money that I can’t manage, and it’s affecting how I live.
- I know exactly what to do and I’m not doing it.
- I’ve accumulated money personally and I want it working properly.
- My business numbers don’t tell me what I need to decide.
Four sentences. Four chairs. Each one names a layer. The first is clinical, where distress has gotten into your life. The second is capacity, where you can see the move and can’t make it. The third is personal wealth, sitting there waiting for a plan. The fourth is the records, the layer every other one gets read from. Most owners start shopping before they’ve read the sentence in their own head, then conclude that help doesn’t work for them.
The Financial Therapist: Money Where It Meets Mental Health
This is the clinical layer, and it’s the one layer nobody else on this list is licensed to stand on. Financial therapy integrates therapeutic and financial competency in one practitioner. It addresses the cognitive, emotional, behavioral, relational, and financial sides of well-being at the same time, in one room, with one person trained for both halves of the conversation.
Financial therapy serves you well if money distress has gotten into your sleep, your relationships, or your daily functioning. You have the same argument with your partner, running on a loop. Compulsive spending, or compulsive restriction. Financial grief. A history that shows up in your body every time a bill does.
What to check before you book: the practitioner’s own state license or credential, in full, and who issued it. The Certified Financial Therapist credential is real and gated, and the Financial Therapy Association is open about who may pursue it, listing therapists, financial planners, counselors, coaches, and social workers among its candidates. The credential tells you a standard was met. It doesn’t tell you the holder is a licensed clinician. Ask.
If you want the field itself explained at length, we wrote it up separately in what financial therapy is and whether it’s for entrepreneurs.
The Money Coach: Where Knowing Turns Into Doing
This is the capacity layer. The information is already in front of you, and something in you won’t pick it up. Coaching is forward-facing and client-directed. The Consumer Financial Protection Bureau, describing its own four-year coaching program, put it plainly: coaches combine money management expertise with general coaching skills, and provide expertise, support, accountability, information, and tools so people can make progress on the goals they named themselves.
Read the verbs there. Support. Accountability. Tools. That’s the whole list, and it stays that short on purpose. Diagnosis and treatment belong to a clinician.
In practice with a business owner, the work is narrow and physical. The invoice that’s been sitting unsent for eleven days. The rate that you already know is too low, said out loud, in a rehearsal, before you say it to a person who might flinch. The report that you open on a Thursday with someone else in the room, until you can open it alone. Capacity determines cash, and capacity is built in specifics.
What it doesn’t include: prescribing medication, treating a diagnosed condition, preparing your taxes, or telling you what to buy in your brokerage account, unless the person separately holds the credential or registration for it. A coach who never says “that one isn’t mine” is a coach with no edges. What a money coach costs and what happens in a session are laid out in what a money coach actually does.
The Financial Advisor: Your Personal Assets, Under a Regulator’s Eye
This layer sits furthest downstream, and it’s the lane with real law in it. It works on money that’s already made it out of the business and into your name. The SEC describes an investment adviser as a firm or person that, for compensation, is in the business of providing investment advice to others about the value of or about investing in securities. Advisers generally must register with the SEC or with state securities authorities. They’re required to act in your best interest and not put their interest ahead of yours. Fees are commonly based on the value of the assets they hold for you, which the SEC itself flags as a source of conflicts worth asking about.
Note what that covers. Your personal portfolio, allocation, long-range planning. Not whether your delivery model is profitable, not what your owner pay should be, not why the cash disappears in the third week of every month. Those are business questions. A good advisor will say so.
The title is softer than the activity. “Financial advisor” is a marketing phrase used across several roles, regulated and not, so ask for the registration, the services in writing, and how the person is paid. Three questions. One email.
The Fourth Chair Most Comparisons Leave Out
If you own a service business, the missing seat at this table is the records layer, and it’s the one everything else gets read from. Business finance, and it looks like this: current books, a cash view you trust, owner pay set as a rule instead of a leftover, and someone reading the pattern forward into the next two quarters. None of the three professions above covers that job. A bookkeeper records, and a fractional CFO helps you decide. That sorting deserves its own piece, and it has one, so this article will stay in its lane.
Worth saying once: a great deal of what gets called money anxiety in an established business is an accurate response to not being able to see. Some distress may ease when the financial picture becomes clearer. Know what that fix reaches, though. A clean record can end the dread of not knowing. It’s never once made an owner willing to look, and it doesn’t touch what money has meant to you since long before you had a business. Those are the other two layers, and they don’t wait their turn.
What Each Title Actually Guarantees
Here’s the short, unglamorous version.
Financial therapist. Financial therapy as a specific area of practice is currently unregulated in the United States, which the Financial Therapy Association states on its own certification page. The individual may well hold a state clinical license. The words on a website are not that license.
Money coach. No universal license, no protected title, no national registry. Ask for which makes the diligence yours: written scope, named deliverables, published or clearly stated fees, and a referral policy for what falls outside the work.
Financial advisor. Advice about securities for compensation is a registered activity, and registration is verifiable before you book. Scope still varies widely between one advisor and the next.
Three different levels of external guarantee. In all three cases, one document settles it: the written scope of services. Ask for it before you book.
Matching the Chair to the Sentence in Your Head
Read these slowly and notice which one sounds like you. You’re not listening for a profession. You’re listening for which layer the sentence came from, because the layer picks the chair for you.
- “I can’t stop thinking about money and it’s affecting my sleep and my marriage.” Clinical layer, and it goes first. A licensed clinician. Financial therapy is one good route in.
- “I know my rate’s too low. I’ve known for a year. I still quote the old number.” Coaching. That’s a capacity gap, and capacity work is bounded and teachable.
- “I have money sitting in accounts and no plan for it.” Personal wealth layer. An advisor, with the registration checked.
- “I don’t actually know what my business made last quarter.” Records layer, and it’s the floor. Bookkeeping and CFO support, before anything else, because everyone else in this list will be guessing without it.
- “All four of those are a little bit true.” Also normal. Sequence it: records first, then capacity, then personal wealth, with clinical care running alongside whenever it’s needed, on its own timeline.
Think of them as a team you assemble. The person coordinating that team is you.
Where Prosperity First Sits
In the capacity layer, in the coaching chair, with the records layer right beside it.
Which Chair Does Your Sentence Point At?
Money coaching with Prosperity First is for established owners who are already earning and still can’t get clean decisions out of clean numbers. Prices are published up front and scope is written down. Four boundaries hold that scope: no diagnosis, no treatment, no tax preparation, no investment advice. That’s the standard this article holds her to, and the one she holds herself to. When something belongs to a clinician or a registered advisor, the honest move is to name it and hand it over.
So say your sentence out loud and hear which chair it points at. If it points at two, that’s ordinary, and the order matters more than the pick. A Clarity Call is a 30-minute resonance check, not a sales appointment. Book one here when you want a second pair of ears on the sentence. A week of sitting with it works too. You get to choose the pace.
Questions owners ask before they book anyone
Q: Where does a financial advisor fit if my problem feels emotional?
A: Usually further along than you’d guess. An advisor’s lane is your personal assets: what you hold, how it’s allocated, and what it’s for over the next ten or twenty years. That conversation goes better once the emotional load has somewhere of its own to go, which is a clinician’s room when distress is in your sleep and your relationships, and a coach’s room when you already know the move and keep not making it. An advisor works with money that exists and stays. Getting it to exist and stay is the other two chairs.
Q: Can a money coach give me investment advice?
A: No, not unless they separately hold the registrations or licenses that allow it. Advice about securities for compensation is a regulated activity under SEC and state rules, and the people doing it hold investment adviser registration or broker-dealer licensing. A money coach can help you get clear on what you want your money to do. What to buy is a different chair.
Q: Is “financial advisor” a regulated title?
A: “Financial advisor” is a marketing phrase used across several roles, and the regulation sits on the activity underneath it. Investment advisers generally must register with the SEC or a state securities authority and are required to act in their clients’ best interest. Verify the registration and ask how the person is paid.
Q: I’m profitable and still anxious about money. Who do I call?
A: Start by checking whether your numbers are actually visible: current books, a cash view, owner pay as a rule, a tax reserve you can see. Anxiety in the dark is usually accurate. It’s a fair reading of a picture you can’t see. If the picture is already clear and you still avoid it, that’s the capacity layer, and it’s coaching work.
Q: Can I work with more than one of these at the same time?
A: Yes, and many owners do. The common pairing for a business owner is clinical care where it’s needed, coaching for decisions and follow-through, and bookkeeping or CFO support underneath both. Ask each professional to state scope in writing so the seams stay clean.
Citations
- “Become a Certified Financial Therapist (CFT) Professional” (Financial Therapy Association). States that financial therapy as a specific area of practice is currently unregulated in the United States, and that the credential exists to professionalize the field and set a standard of practice and code of ethics. It also names who may pursue certification, including therapists, financial planners, counselors, coaches, and social workers. https://financialtherapyassociation.org/become-a-cft/
- “Financial Coaching Initiative: Results and lessons learned” (Consumer Financial Protection Bureau, May 2021). Describes financial coaches as combining money management expertise with general coaching skills, providing expertise, support, accountability, information, and tools toward goals the client identifies. Coaches were embedded in 60 host organizations and served over 23,000 people across four years. https://www.consumerfinance.gov/documents/9762/cfpb_financial-coaching-initiative-lessons-learned_report_2021-05.pdf
- “Investment Advisers” (U.S. Securities and Exchange Commission, Investor.gov). Defines an investment adviser as a firm or person that, for compensation, is in the business of providing investment advice about securities, confirms advisers generally must register with the SEC or state securities authorities, and states they are required to act in the client’s best interest. https://www.investor.gov/introduction-investing/getting-started/working-investment-professional/investment-advisers
Related reading
- What Is Financial Therapy, and Is It for Entrepreneurs?
- What Does a Money Coach Actually Do (and What Does It Cost)?
- Is a Fractional CFO Actually Worth It at My Size?
- Fractional CFO Services
- Money Coaching With Prosperity First
From the author of the forthcoming book Profit Is Protest.